
Over the past year, AI web products have gone through several rounds of “traffic rollercoasters.” Many projects hit tens of millions of visits during hype cycles, but only a handful turned attention into sustainable cash flow.
The latest July 2025 data tells us again: the moat for winners comes from turning capabilities into outcomes, not just turning hype into clicks.
We break it down across three lenses—scale, structure, and momentum—to answer one question: who turned traffic into money, and how did they do it?
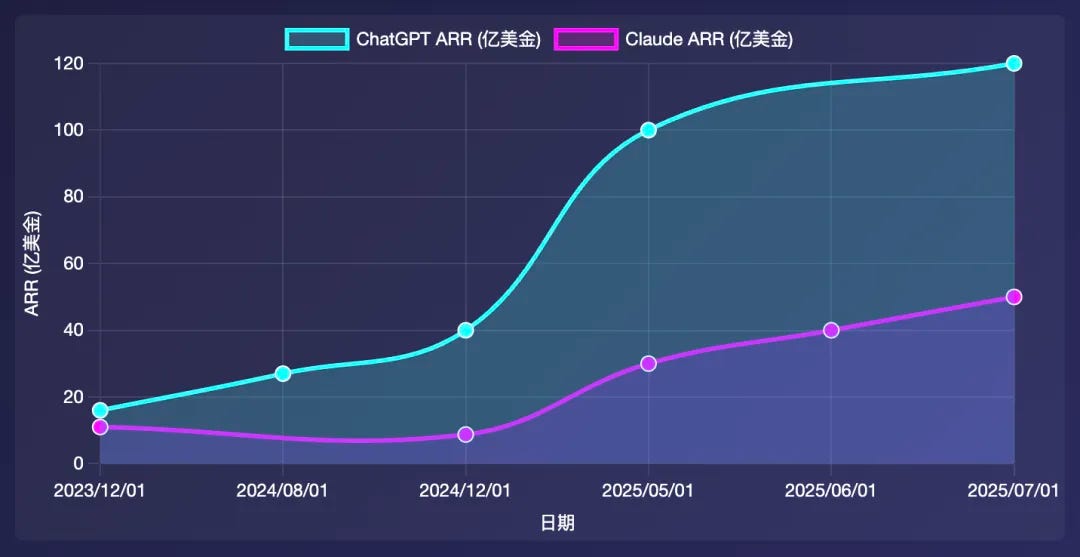
The Top 100 AI Web products generated a combined $24.2B ARR.
Top 5 share: 77.7%
Top 10 share: 82.4%
Top 10 by ARR: ChatGPT, Claude, Grammarly, Midjourney, Cursor, Dialpad, 6sense, Mercor, Glean, Moveworks.
👉 General-purpose “gateways” (ChatGPT/Claude) pair with practical scenarios (writing, image generation, code, customer support, marketing, recruitment, enterprise efficiency, agents). Gateways bring scale; scenarios lock in cash flow.
By category (ARR):
Chatbots ≈ $17.01B
Code assistants ≈ $1.03B
Writing ≈ $760M
Image generation ≈ $717M
Customer support ≈ $641M
Marketing tools ≈ $626M
Video generation ≈ $482M
Model training ≈ $432M
Agents ≈ $345M
Smart search ≈ $194M
Takeaway:
Chat is the volume gateway.
Code, writing, image, video = measurable output = billable results.
B2B functions (support, marketing, sales, recruiting) = stable recurring revenue.
Instead of % growth (which small bases distort), we tracked absolute MRR increase (in $10K).
Highlights:
Mercor (recruitment): +$1.598M, +126% MoM
Cursor (code): +$4.167M, +41% MoM
Replit (code): +$935K, +116% MoM
gethookd (marketing): +$384K, +272% MoM
Higgsfield (video editing): +$326K, +264% MoM
Dialpad (support): +$3.003M, +19% MoM
Momentum concentrated in categories with immediate, visible results: code, video, marketing, customer support, and sales.
Gateway-driven: ChatGPT, Claude—scale creates revenue; monetization via enterprise features, plugins, APIs.
Outcome-driven: Cursor, Replit, Midjourney, Dialpad, 6sense, Glean, Moveworks—sticky subscriptions tied to tangible deliverables.
Momentum-driven: Mercor, Higgsfield, Akool, Rezolve AI—fast growth from niche but result-oriented use cases.
Total visits (Top100): 91.41B
Top 10 products: 84.1% of traffic
Chatbots: 77.8% of total traffic
Examples:
Character.AI: top 3 in traffic, but weak monetization (youth-heavy base, low willingness to pay).
Perplexity AI: much smaller traffic, but higher ARPU thanks to pro-focused subscriptions and APIs.
Janitor AI: emotional-companion app, surged into top 10 in 2 months; monetization potential still unclear.
In July, Chinese players like Doubao, Kimi, Baidu AI Search were highly active in traffic rankings. But on a global revenue basis, B2B-heavy overseas products dominate.
Why? Because revenue streams differ:
Subscriptions don’t fully capture ad models, e-commerce commissions, or enterprise contracts.
Chinese teams focus more on ecosystem entry points and full-stack platforms than single-product subscriptions.
Move from Q&A to Task Delivery: billable middle layers (workflow orchestration, auditing, progress tracking).
Embed into Workflows: enterprise stickiness comes from ROI-driven use cases (support, sales, marketing, meetings).
Chase momentum tracks: video editing/generation, code assistants, and marketing automation show consistent new MRR gains.
Traffic is still the foundation—but recurring revenue follows results.
Future winners won’t just “attract attention,” but embed themselves into enterprise workflows and deliver measurable ROI.
📊 Full July 2025 AI Web Rankings—including revenue, traffic, and growth breakdowns across 100 products—are now open and free at 100aiapps.cn.
✅ Permanently open-source
✅ Based on independent third-party data only
✅ Rankings remain fully neutral, free of commercial bias
Because in the end, data doesn’t lie, and trends never arrive late.