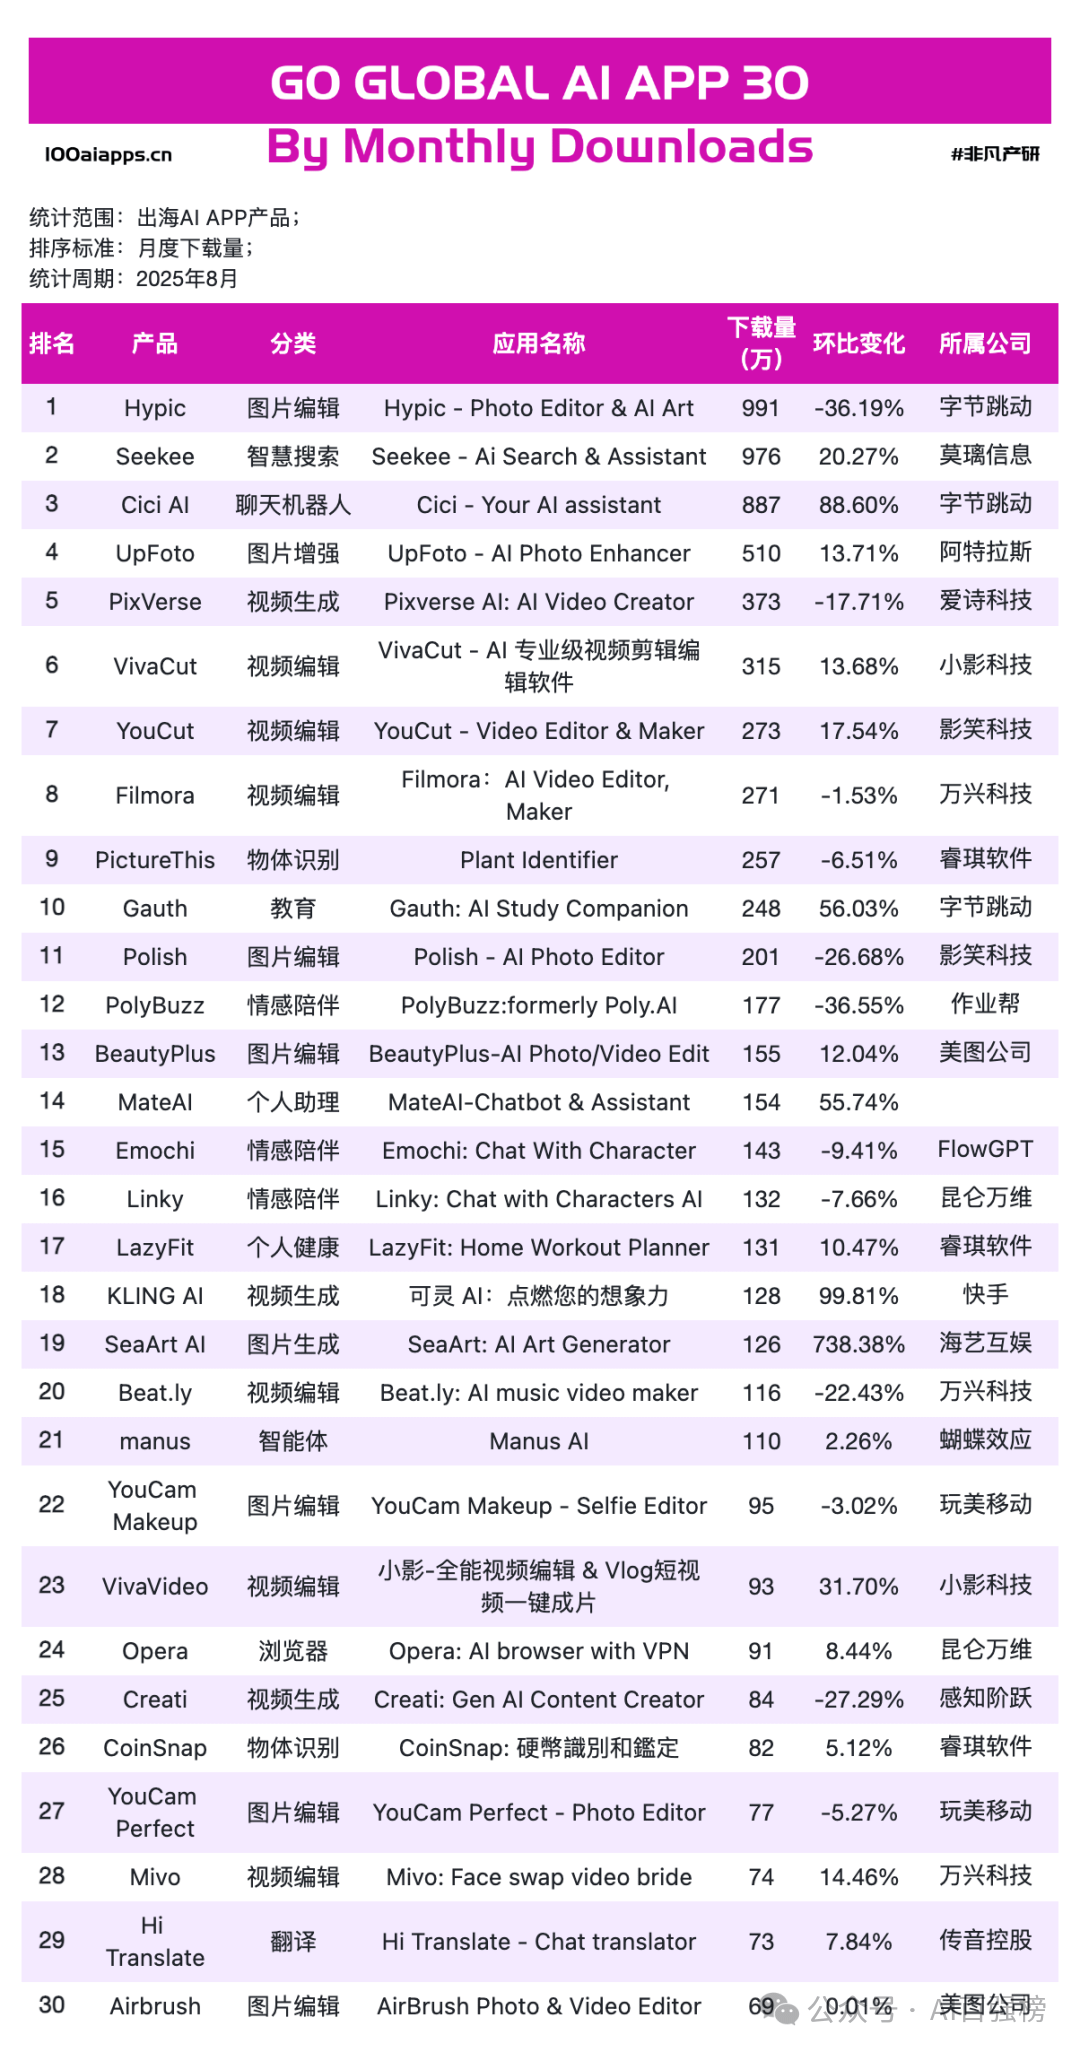
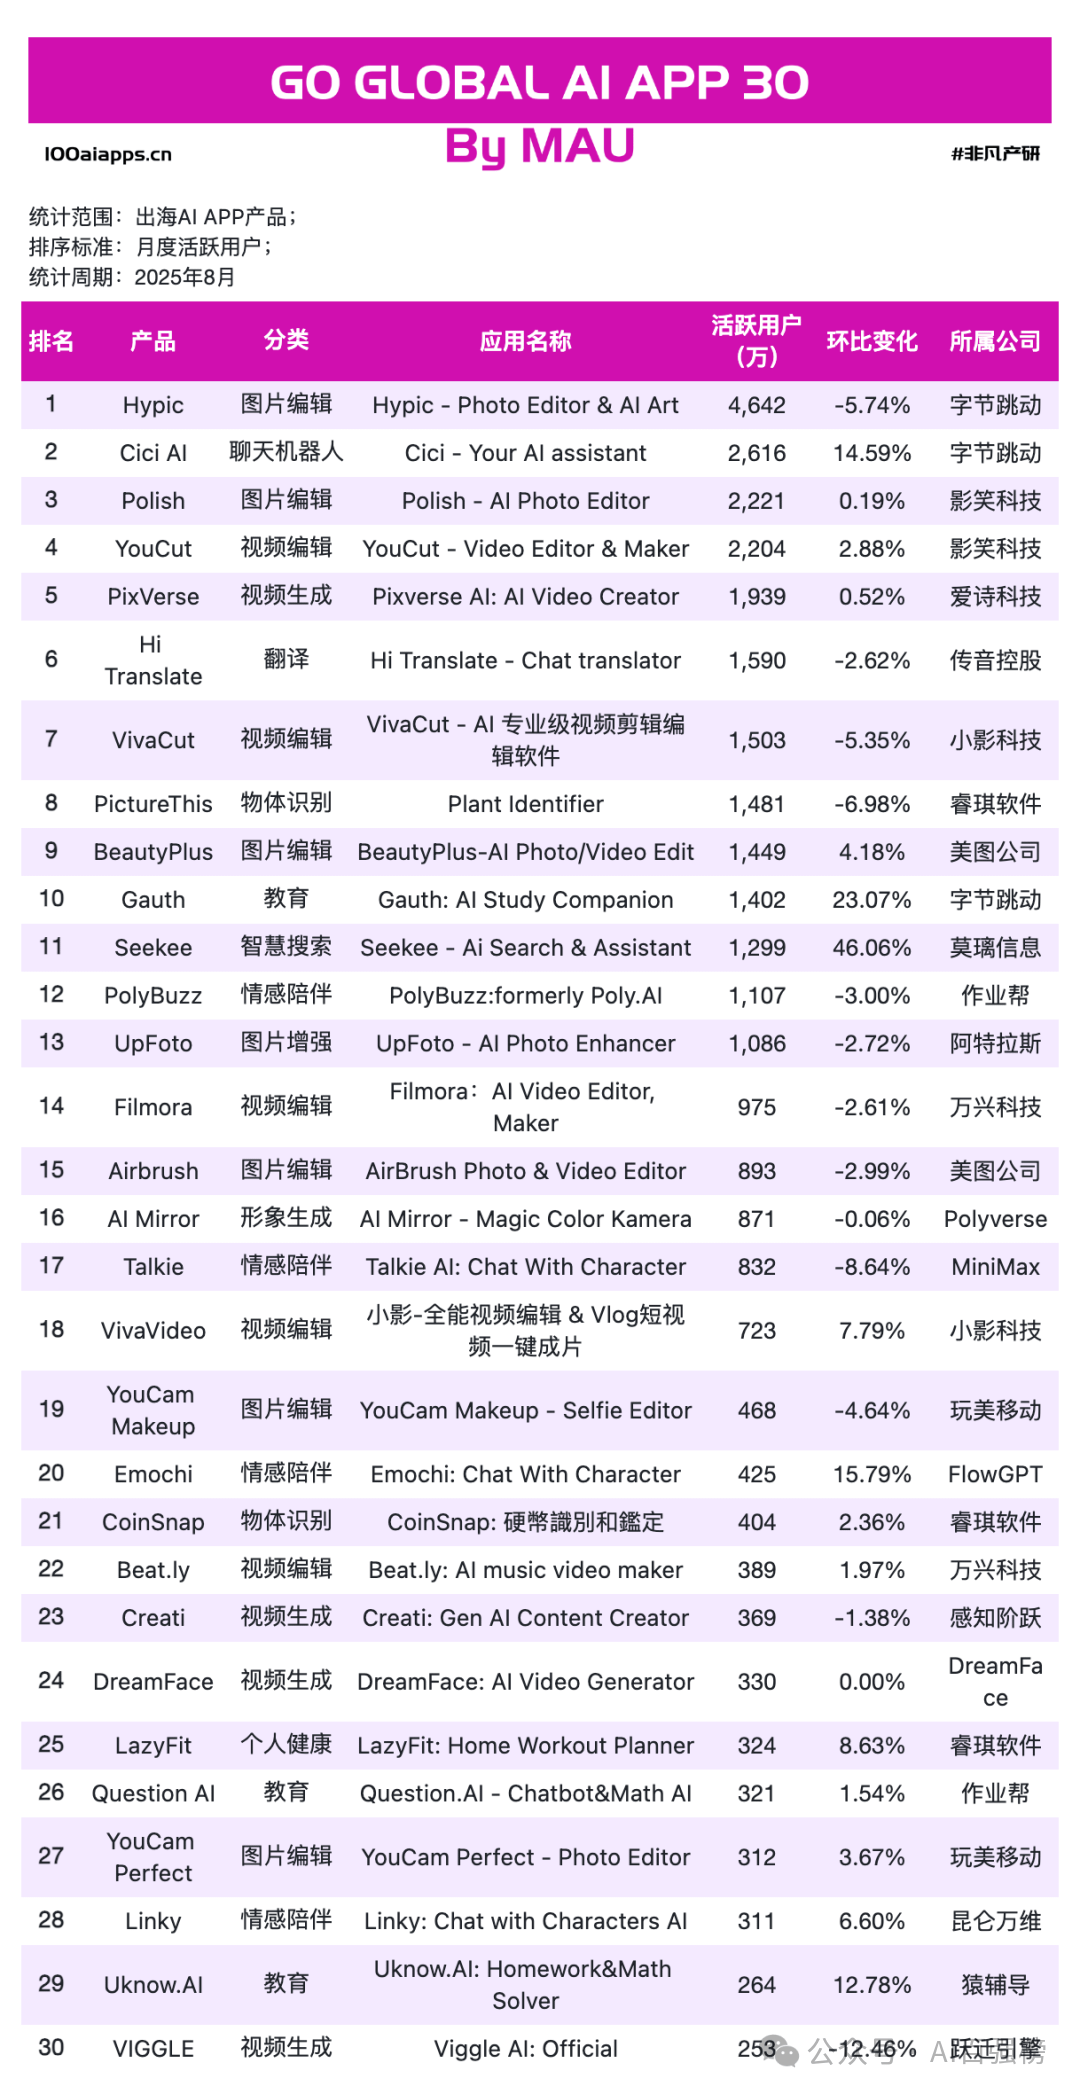
August’s landscape for overseas AI apps is clear: on the web, content distribution and “entry-point” capabilities are consolidating growth; on mobile, media creation and vertical tools are soaking up user time. In terms of concentration, the Web Top 100 shows the Top 10 account for ~45% of total visits, while on the App side the Top 10 take ~69% of total downloads and 64% of total MAU. Monthly active user contribution is even more top-heavy (Top 20 on web ≈ 70%; Top 20 on apps > 90%). This ties to “overseas multi-app matrix operations—paid acquisition + distribution in sync,” and to Chinese developers’ deep accumulation in high-frequency verticals like imaging, search, and education.
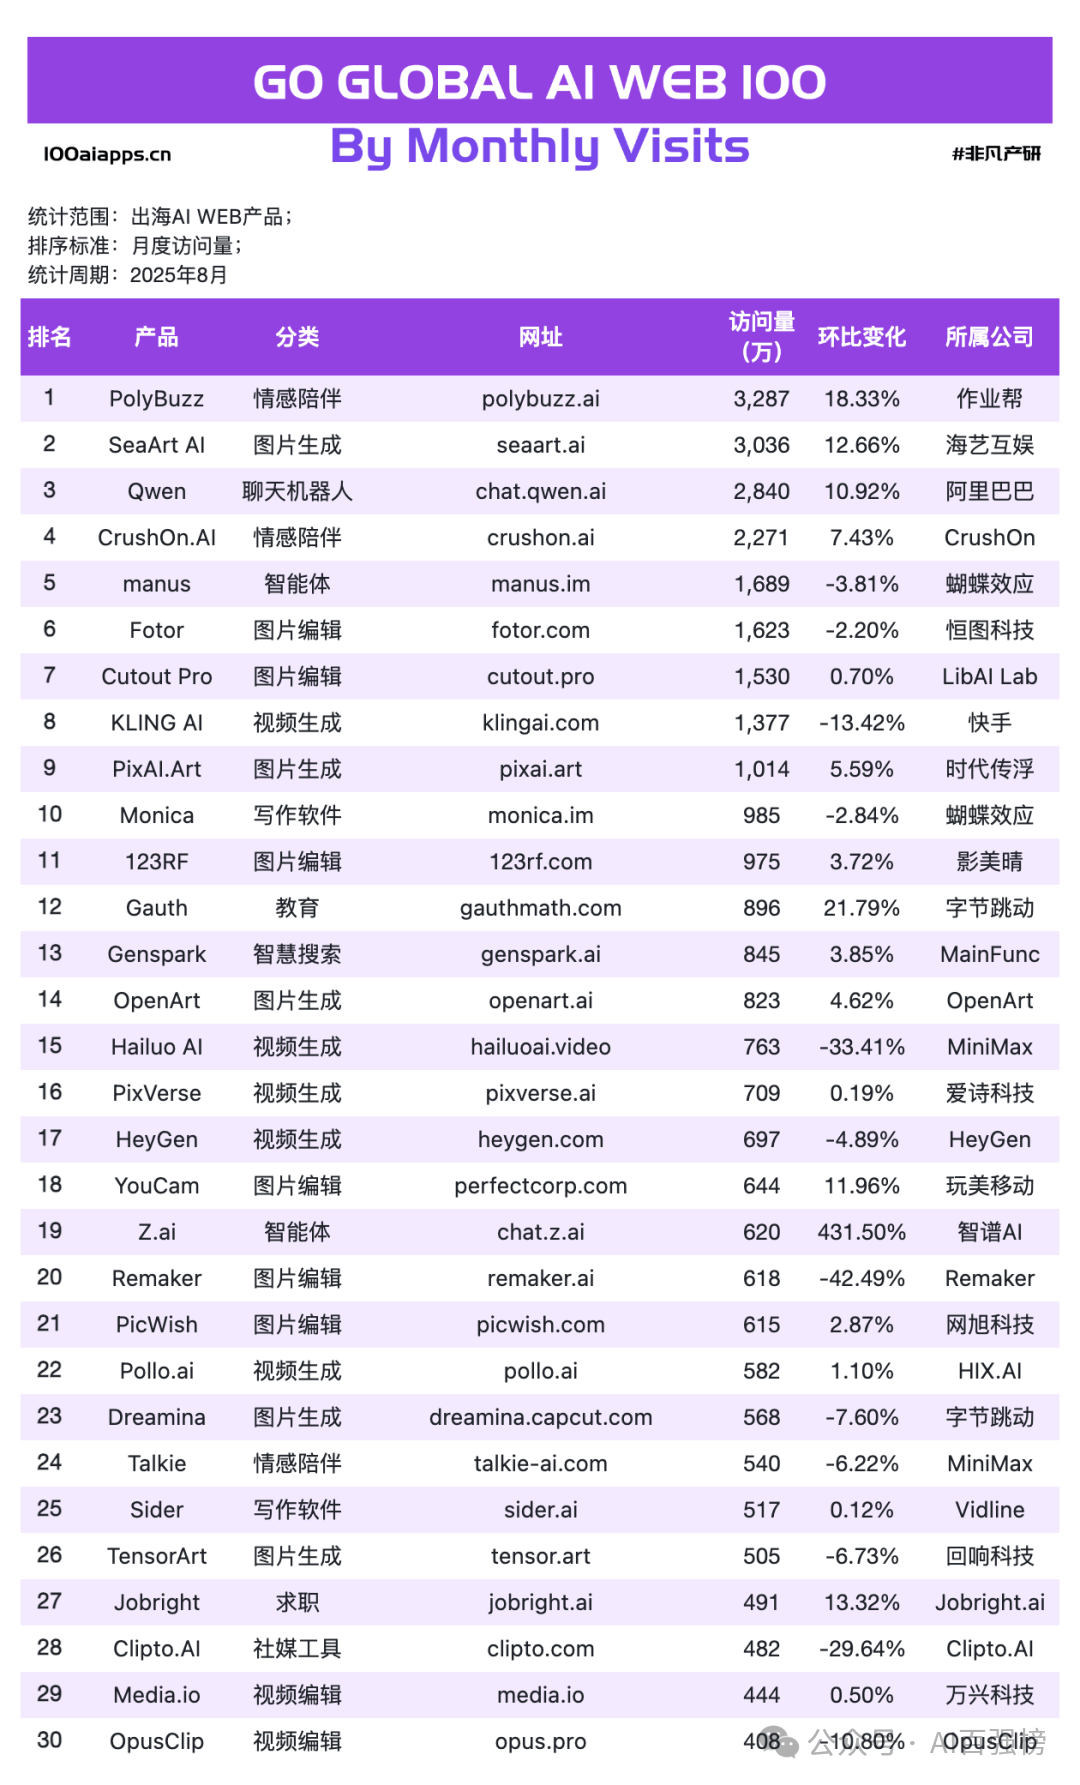
If you just look at scale, PolyBuzz (AI companionship) and SeaArt (image generation) lead the pack: August visits of ~32.9M and ~30.4M respectively; behind them are Qwen (conversational portal, ~28.4M), CrushOn (companionship, ~22.7M), and manus (agents, ~16.9M). Collectively, these five map to three core needs: long-tail time in light social/companionship, a general dialog/search entry, and the expressive urge of image generation.
By category share within the Web Top 20, AI companionship, image editing/generation, and video generation together capture more than half of total visits; chatbots/agents and smart search form the second tier. In short, content that can be shared and tools that create shareable content remain the web’s growth engine.
On the growth side, two types are worth watching:
Small base, hyper-growth newcomers: e.g., MaxAI.me visits +895% MoM, Class Companion +814%—still in the 1–3M range but rising fast, signaling product-channel fit has clicked.
Not small, still accelerating expanders: Z.ai at 6.2M visits (+431%); Lovart 3.23M (+68%)—and it introduced the nano banana model in September, likely another step-up; Tripo 2.59M (+49%). They’ve crossed beyond one-off virality into sustained scale-up territory.
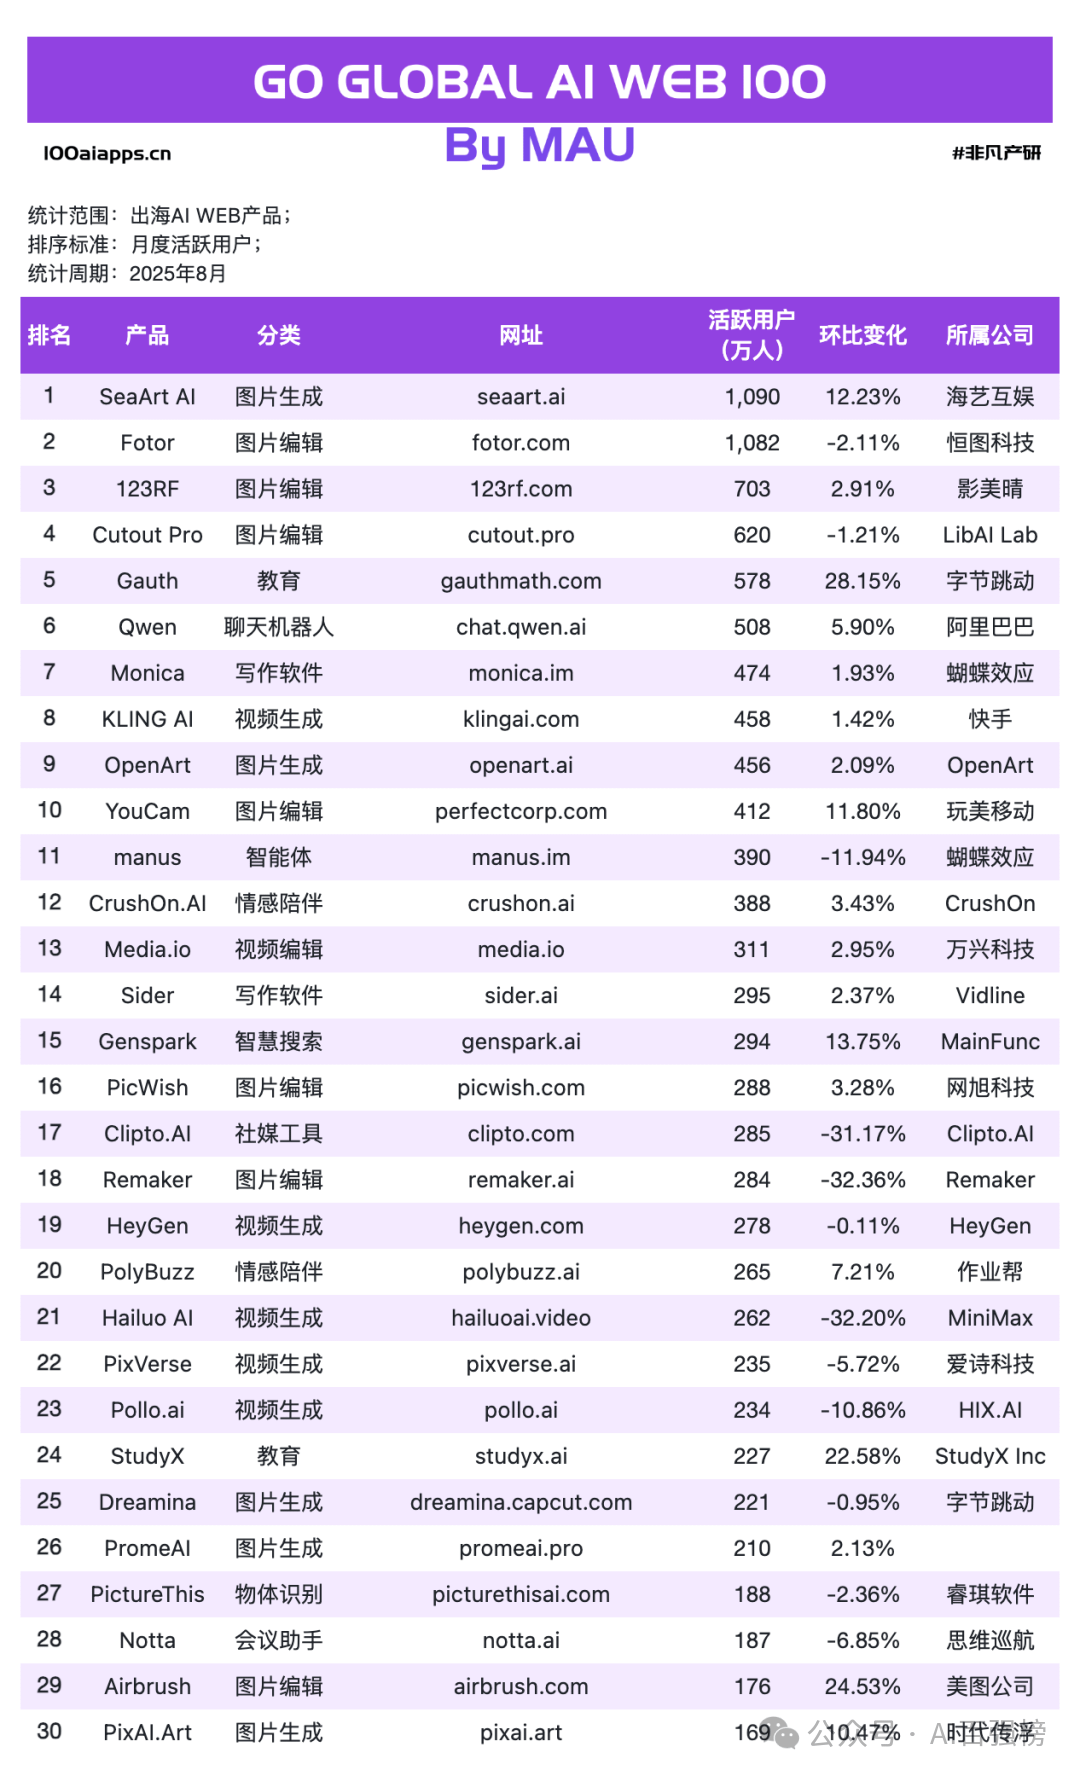
On MAU, SeaArt and Fotor both surpassed 10M MAU, while Qwen, KLING AI, and OpenArt continue a steady climb. MaxAI.me and Z.ai saw MAU spikes in tandem (+1390% and +229% respectively), validating these aren’t one-time traffic pops.
One detail: the Web Top 10 only covers ~45% of the total—far lower than mobile. The web’s long tail is longer, and the “slow variables” of SEO, content ecosystems, and social sharing still matter.
On mobile, imaging/editing/generation sits squarely at center stage: Hypic (ByteDance) posted ~46.4M MAU and ~9.91M downloads in August. Even with a pullback in downloads, MAU shows strong resilience. Polish, YouCut (影笑科技), and VivaCut (小影科技) form the mid-tier backbone of video/image editing; PixVerse (爱诗科技) reached ~19.4M MAU, showing that video generation has shifted from novelty to a must-have expression.
AI search and homework/learning are the second thread: Seekee (莫璃信息) hit ~13.0M MAU (+46%), ~9.76M downloads (+20%), indicating “search + assistant” has found a mobile rhythm. Gauth (ByteDance) posted ~14.2M MAU (+23%), ~2.48M downloads (+56%), as composite education scenarios (photo-solve, explanations, progress tracking) take shape.
On the growth board, SeaArt stands out on mobile: downloads +738% (~1.26M), MAU +306% (0.88M), echoing its high web traffic to form a cross-platform flywheel of content → community → conversion. At the same time, KLING AI (Kuaishou) downloads hit ~1.28M (+100%), and Cici (ByteDance) reached ~8.87M (+89%)—both video and general-purpose chat apps clearly accelerated in August.
By brand, ByteDance’s portfolio captured ~41% of MAU within the App Top 10 (Hypic + Cici + Gauth). This isn’t a single-product win; it’s the systemic result of distribution, paid acquisition, and cross-app traffic routing. Overall, concentration for the App sample’s Top 10 sits near 69% (downloads) / 64% (MAU), suggesting the mobile “first half” is ending and we’re entering the “second half” where operational efficiency and retention decide outcomes.
Viewed across web + app, SeaArt, KLING, PixVerse, PolyBuzz, Gauth, and Seekee all exhibit cross-platform linkage to varying degrees:
SeaArt is the classic flywheel: 30M+ web visits and 10M+ MAU fuel content and community; the app side catches creation and distribution. August’s mobile acceleration shows growth isn’t just a single-channel pull.
KLING / PixVerse follow a natural path of “video generation → video editing → platform distribution,” with web driving exposure/tutorials and the app delivering production/export.
PolyBuzz / CrushOn (companionship) enjoy shareable dialogs/storylines on the web, while the app carries more private, continuous usage.
Seekee / Gauth (must-have utilities) are the reverse: the app is the main arena, the web is for discovery.
Net-net: web works as the “front desk of traffic + community showcase,” while apps act as the “efficiency back-end + production tool.” Products with durable growth tend to build verifiable two-way loops across both.
Treat entry-point capability as part of the product, not just an ad channel. The climbs of Qwen and Z.ai show users will pin a “conversational/search portal” to their bookmarks. Embedding your capability into conventional entry points (browser extensions, system shortcuts, in-app widgets across multiple apps) sets the ceiling for organic growth.
**On mobile, the race is the edit-to-export-to-share loop—**not “who has more features.” The staying power of Hypic, Polish, YouCut owes much to short editing paths, reliable export, and broad platform compatibility. To join the app-side leaders, sweating load speed, export success rate, and the template ecosystem matters more than adding one more flashy effect.
Match growth rate to base size. Explosive MoM spikes like MaxAI.me and Class Companion usually come from structural supply/channel improvements; while “not small, still accelerating” cases like Z.ai, Lovart, Tripo suggest product-market fit is locked. Track both, but allocate resources differently: the former to retention & repeat use validation, the latter to scaling & commercialization.
If you’re building content-community + generative tools, SeaArt’s cross-platform flywheel is a deconstructable playbook: web for showcasing works + social spread, app for high-frequency creation + export efficiency, with templates, challenges, and leaderboards looping the two. If you’re building search or education, Seekee + Gauth show the certainty of low-friction entry + must-have solving; on mobile, “low-friction” often means shorter input→output paths, clearer guidance, and verifiable outcomes.
August 2025 AI Top 100 details:
Overseas AI Web Top 100: Top web products by visits and monthly active users (MAU).
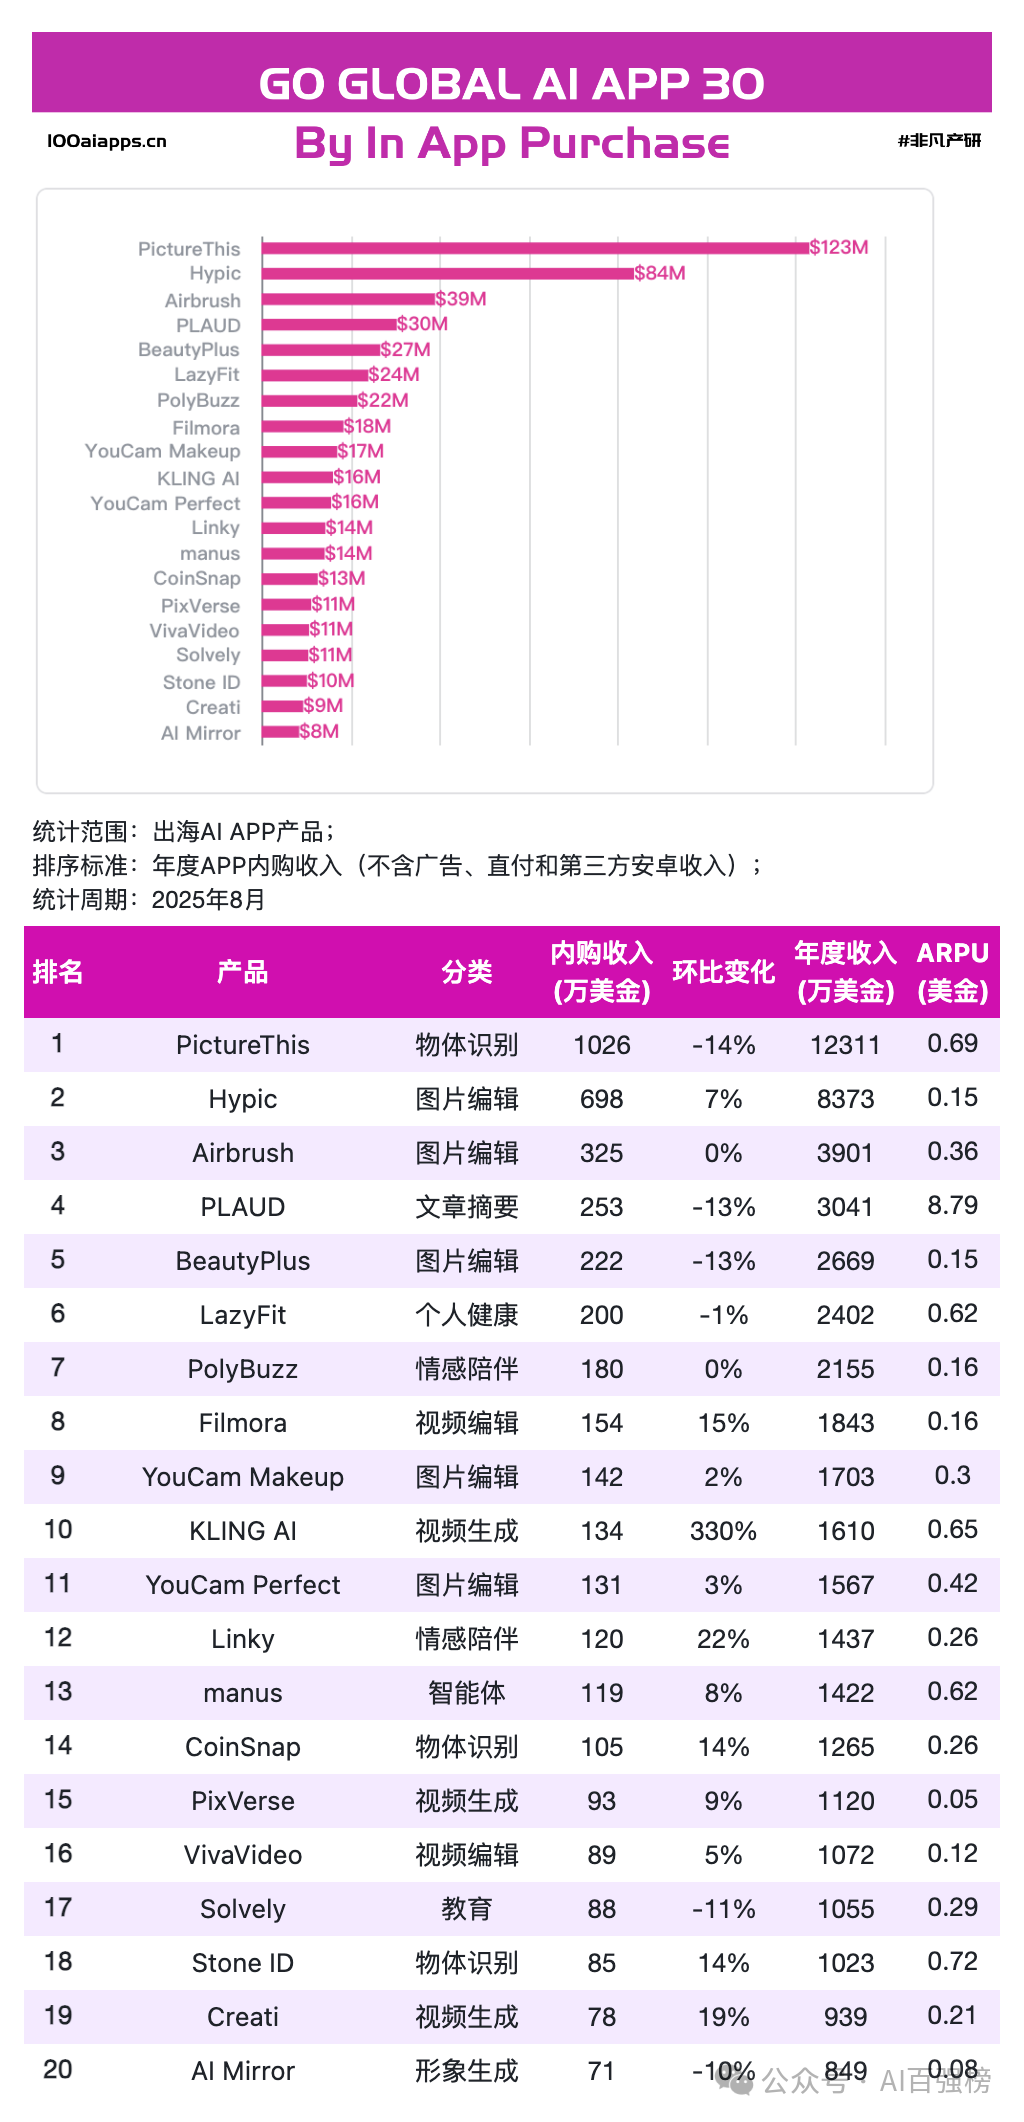
Overseas AI App Top 30: Top mobile products by downloads and MAU.
Recognition & trust. UNIQUE RESEARCH’s data and insights are widely cited by leading investment firms, academic institutions, and media in China and abroad, serving as a benchmark for market analysis, investment decisions, and trend evaluation. Our partners and citers include (not limited to):
Brokerages & i-banks: GF Securities, CSC Financial, Huayuan Securities, Haitong Securities
Authoritative media: China Securities Journal, TMTPost, Jiemian News
Our commitments to openness and rigor:
The AI Top 100 is permanently open-sourced and free, with full methodology and raw data for end-to-end reproducibility.
Data sources are strictly limited to independent third-party measurement platforms; we do not accept company-self-reported data.
The ranking system remains strictly neutral; we do not accept any commercial cooperation or payment that could influence results.
How to use the AI Top 100?
Investors/analysts: A clean, reverse-engineerable data baseline for building models, surfacing under-the-radar projects, and cross-validation.
AI founders/product managers: Precisely locate competitors and replicate our methodology to analyze your own market performance and optimization paths.
Researchers/students: Full openness makes this an excellent free dataset for academic and market studies. We encourage novel research built on this data.
Access the full charts and underlying data at 100aiapps.cn. All visible data is copyable and free for personal learning and research. For commercial use, please contact UNIQUE RESEARCH in advance for authorization. We also welcome listed teams, under compliant use, to reference their rankings in pitch decks, hiring materials, and more as an authoritative proof of traction.